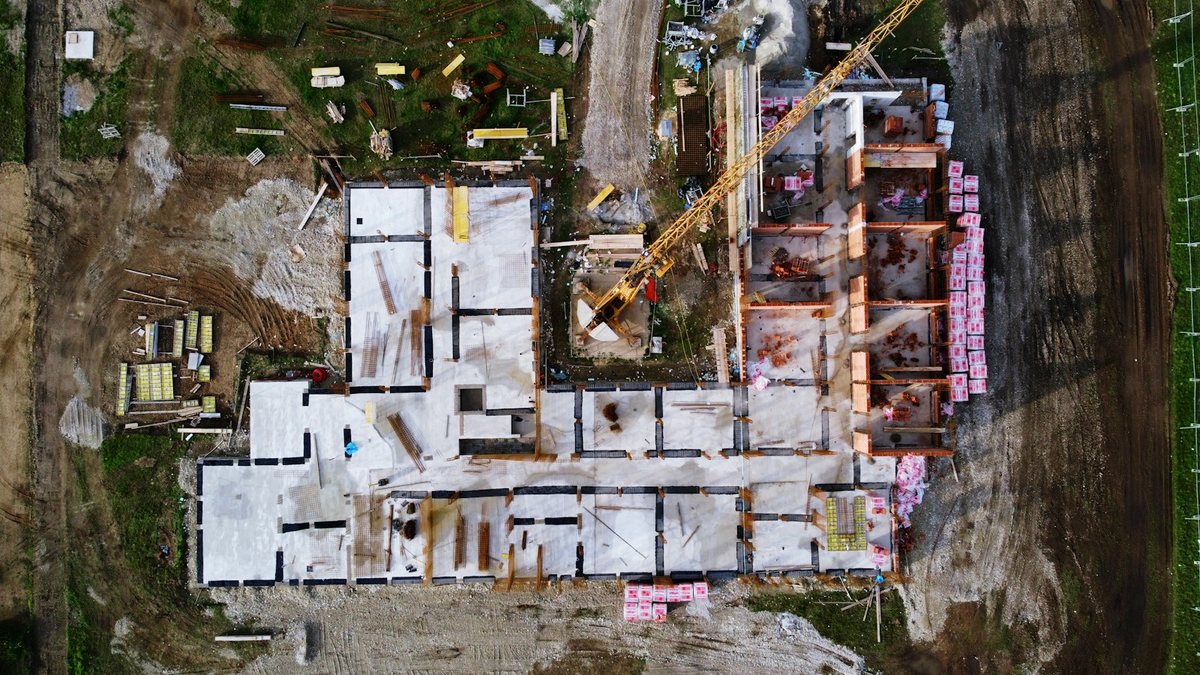
ICON announced a $200 million Series D on 13 October, co-led by Baillie Gifford and funds managed by BlackRock. The Austin company has been 3D-printing buildings for the better part of a decade and the round is large enough to be read as a vote on whether that works.
The release’s subheadline bills it as the launch of the “First Commercial Rollout of Titan Print System.” That programme has a history a reader should have: ICON announced it on 11 March 2026, in a release headlined “ICON Announces First Commercial Rollout of its 3D-Printing Construction Technology for Builders”, which opened reservations against a $5,000 deposit and put customer training in Q3 2026 with first system deliveries in early 2027.
What the Series D adds is the manufacturing behind that timetable. The body of this release says the financing “will initiate the production and manufacturing of Titan, ICON’s multi-story robotic construction system, at the ICON factory located in Austin, Texas.”
For most of its history ICON has been a builder that owns printers. This is the capital to become a manufacturer that supplies them, against a delivery date it set in March.
The Shift Is From Building Houses to Supplying the Machine
Titan is described in the release as a multi-story robotic construction system, and the stated use of funds puts manufacturing first: manufacturing and deploying robotic systems, a large-scale R&D facility in Austin, continued development of Titan and of Project Olympus, and expansion across Texas, Florida, Washington D.C. and additional US markets.
Chief executive and co-founder Jason Ballard frames the decade behind it in the release as a transition from belief to evidence: “Construction automation has crossed from potential into proven reality.” He also says the funding will put more Titan systems in builders’ hands, and ends with a line that is unmistakably a fundraising thesis rather than a product claim: “I believe we can imagine an end to the global housing crisis in our lifetime.”
Read against the company’s own history, the manufacturing turn is the news. ICON has spent years as the general contractor on its own technology — Wolf Ranch in Georgetown, Texas, built with Lennar and described in the release as “the world’s first and largest community of 3D-printed homes”; more than a hundred homes for people experiencing homelessness through Community First! Village in Austin; US Army work. Each of those required ICON to show up and build. A printer sold or deployed to a builder does not.
This is the distinction that has separated the two halves of this category. Reframe Systems raised $40 million for microfactories it runs itself, and Hyperion Robotics raised $7.4 million to print infrastructure components in microfactories rather than cast them in plants. Monumental’s $32 million Series B sends robots to sites its own operators supervise. The alternative model — put the production capability in the hands of a builder who already has the land, the designs and the sales — is what Promise Robotics agreed with D.R. Horton on the same day, from the other direction: Promise keeps the factory and sells capacity, ICON intends to sell the machine.
What the Release Does Not Say, and What the Record Does
The release does not state a valuation and does not state total capital raised. That is a fact about the document, not about the record. Bisnow ran it the same day under the headline “BlackRock Invests In 3D-Printing Construction Startup Valued At $1.4B,” and its text says the round “brings the company’s total funding to $700M at a $1.4B valuation, CNBC reported” — so Bisnow is relaying CNBC on both figures, even as it carries the valuation in its own headline. Readers should take the $1.4 billion and the $700 million as those outlets’ reporting rather than as figures ICON has confirmed.
Nor does the release disclose the agreement’s structure beyond naming the co-leads and listing other participants: Capital Factory, CAZ Investments, Moderne Ventures, Moonshots Capital, Norwest, Overmatch, The Syndicate and Tiger Global, “among others.”
Two names in that list are worth separating from the rest. Moderne Ventures led ICON’s $35 million Series A in August 2020. Norwest led the Series B of more than $200 million in August 2021. Both are back. The genuinely new capital at the top of this round is institutional in a different way: Baillie Gifford describes itself as an independent partnership with no outside shareholders, investing for the long term and running a private-growth book alongside its public funds; the release’s own boilerplate puts its assets under management at $262bn as at 30 June 2026. BlackRock-managed funds bring a different kind of balance sheet again to a construction-robotics cap table.
Luke Ward, Private Companies Investment Manager at Baillie Gifford, is quoted on exactly that proposition: “The industries hardest to change often have the most to gain.” The rest of his quote argues that ICON’s system works with, rather than against, the business realities of a project, so that builders can take on more work and owners get better value.
Prime Is the Division With Signed Contracts Behind It
The release describes three business units: Build (residential, commercial and hospitality), Tech (the unified construction platform) and Prime (defense and space). It says ICON Prime has been awarded more than $370 million in government contracts.
That is the part of the company with the least speculative revenue attached, and the Fort Bliss programme is where to look for the detail. The Series D release notes that ICON broke ground on 10 barracks there in January 2026. ICON’s own 28 July release puts numbers on the delivery: ten open-bay buildings, more than 78,000 square feet of covered area, 5,772 square feet of conditioned space each, housing up to 560 service members, printed in 58 days against a $62.8 million production contract the Army awarded in December 2025 through an Other Transaction Authority agreement with the US Army Corps of Engineers, Fort Worth District. ICON describes the deployment as the largest robotic construction deployment in Department of War history; that characterisation is the company’s.
Will Hurd, President of ICON Prime, is quoted in the July release saying “That is not an incremental improvement.” Government work of that shape — a fixed scope, a named contracting authority, a dollar figure — is about as close as this sector gets to proof that a printed building survives a procurement process.
The Figures ICON Supplies, and Where It Says They Come From
Four company figures carry most of the weight in the release, and all four are ICON’s own.
- “ICON is on pace for 4x revenue growth in 2026.” No revenue base is given, so the multiple cannot be converted into a number.
- “The company has built more than 270 homes and structures across five states and two countries.” The states and the second country are not enumerated.
- Titan is designed to “reduce the construction time of an average home by six weeks at 40% lower cost than the national average.” The release footnotes this: “Internal cost modeling compared to the National Association of Home Builders Annual Report.” That is more disclosure than most vendor comparisons carry, and it is worth reading as what it says — a model, against a published benchmark, run by the company whose machine it flatters.
- FormCrete, ICON’s proprietary printing material, is given as rated for winds of 175+ mph against 40 mph for traditional stick framing, and 2+ hours of fire resistance against 0.5 hours for conventional construction.
The release also sets out the market case in four numbers, each carrying a footnote marker pointing to external sources: a $16 trillion global construction industry, a US shortfall of roughly 4 million homes, just 10% of US construction workers under 25, and 41% of the current workforce expected to retire by 2031. Those are the demand-side figures physical-AI pitches in this sector routinely open with, and the last two are the ones that matter for automation specifically — a labour pool that is not replacing itself is a constraint no amount of recruiting resolves.
What Would Make This Round Look Right
Analysis, clearly labelled as this publication’s own: the test of a $200 million round aimed at manufacturing is not how many homes ICON prints next year. It is how many Titan systems leave Austin under someone else’s operation, and whether those builders re-order.
Selling the machine is a harder business than using it. It requires a service organisation, spare parts, training, uptime guarantees and a customer who will absorb a stopped printer on a live schedule — the same wall that capacity-priced robotics deals are designed to get around by never transferring the asset at all. ICON is choosing the model that scales faster if it works and strands more capital if it does not. The deliveries ICON put in early 2027 are the thing to watch. This release does not name the builders taking the first systems; the March one named one, quoting Spencer Padgett, co-founder of Ghost Factory, on integrating Titan machines into its building platform to stabilise structural costs.