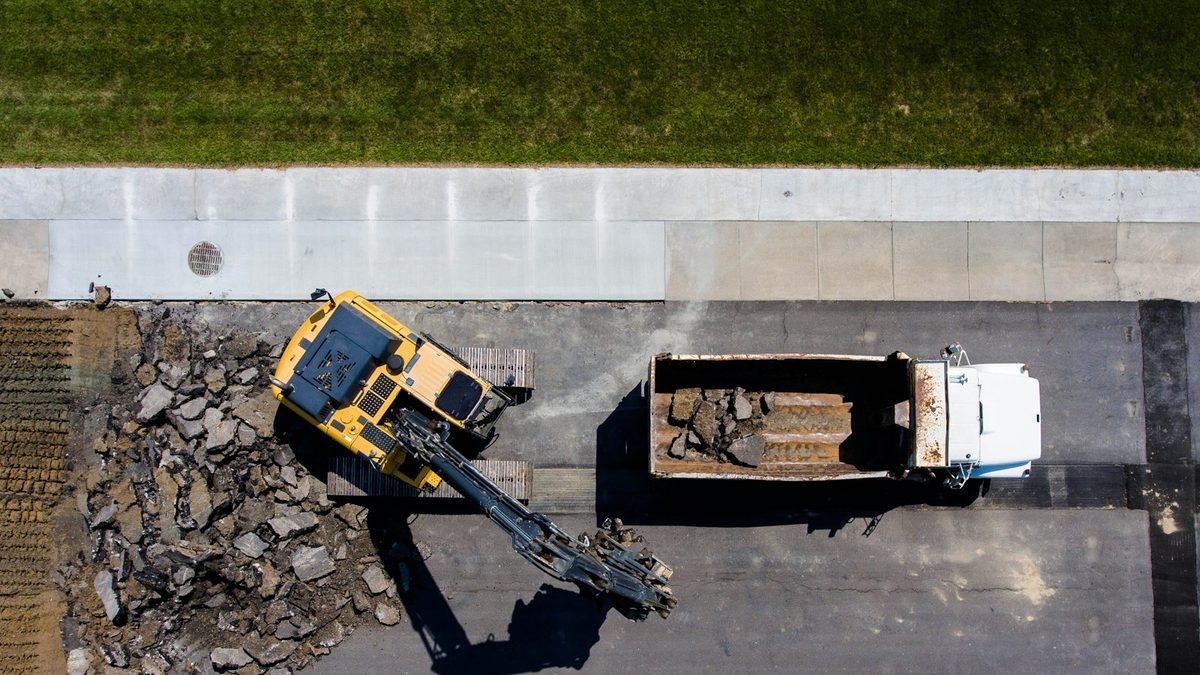
Autonomous Solutions, Inc. — ASI, of Mendon, Utah — announced on 24 September that it has formed a joint venture with SoftBank Group Corp. (TSE: 9984) focused on “the development and commercialization of autonomous construction equipment for large infrastructure projects,” and that SoftBank has separately invested $225 million in ASI itself.
The release is careful about which money is which, and it is worth being equally careful reading it. There are two transactions. The joint venture “has been capitalized by SoftBank Group for meaningful scale across a number of construction use cases.” That is a different pot from the $225 million, which the release says went into ASI “providing capital to grow its commercial operations across the broader construction market.”
What the announcement does not give is the size of the first pot. It names no figure for the joint venture, no ownership split, no name for the entity, no valuation for ASI and no round letter. Dealroom’s note on the deal — headlined $230M, though its body gives the same $225 million — says the same thing in as many words: “the venture’s size, ownership split, and name were not disclosed.” And and no valuation or series designation appears in any coverage of the deal we could find. So the publicly identified number is $225 million, and SoftBank’s total commitment to this pair of transactions is larger than that by an amount that has not been made public.
What ASI Actually Sells
ASI’s product is Mobius®, which the company describes as the platform that “defined Industrial Autonomous Fleet Orchestration (IAFO).” The distinction the company draws is between automating a machine and orchestrating a fleet of them. From the release: “Most autonomous solutions are designed around a single vehicle, a closed ecosystem, or a future roadmap. ASI was built for real-world fleet orchestration across mixed vehicle environments, existing infrastructure, and long-term operational scalability.”
CEO Mel Torrie put the commercial version of that in the announcement’s only quote, which opens by calling the venture “built for scale, engineered for longevity, and open to every major equipment brand on the jobsite” before getting specific:
”…Together, we offer automated OEM-agnostic heavy equipment solutions that let customers deploy mixed fleets of haul trucks, dozers, loaders, compactors, and more—all operating autonomously together across complex tasks from earthmoving to vertical construction. Backed by world-class capital and 25+ years of proven technology, we’re not just advancing autonomy—we’re inviting the industry’s leading builders of large infrastructure projects, like roadways, airports, railways, waste management, and other adjacent applications, to shape the future of construction with us.”
Two things in that sentence are doing real work. OEM-agnostic means the autonomy is sold as a retrofit layer over whatever iron a contractor already owns, rather than as a feature of a machine they have to buy. Mixed fleets means the claim is not that one truck can drive itself, but that a yard full of different manufacturers’ trucks, dozers and compactors can be coordinated from one system. Those are the two hardest parts of the problem, and they are also the two claims a reader cannot verify from a press release — the announcement names no customer, no site and no deployment for the construction business.
ASI was founded in 2000 “by a group of engineers who took technologies developed at Utah State University into the commercial sector,” says the boilerplate on last week’s release, which lists heavy construction, agriculture, logistics and landscaping among its markets. The company’s site bills it as the “Worldwide Leader of Industrial Autonomous Fleet Orchestration” and claims “25+ years of autonomous experience” and “1,000+ vehicles deployed.”
From Mining to Construction, With SoftBank Already Inside
The thing that makes this more than another physical-AI cheque is where ASI’s autonomy came from, and what it gave up to get here.
In May 2024, ASI announced the sale of its ASI Mining business unit to Epiroc, the Swedish mining-equipment group. Epiroc, ASI’s own release states, “acquired a 34% stake in ASI Mining in 2018 and will now take full ownership of the company.” ASI said the divestiture positioned it “to accelerate their expansion of the Logistics, Agriculture, Landscaping, Construction, and Automotive Test product offerings.”
Mining is where a great deal of fleet autonomy grew up: enclosed sites, repetitive haul cycles, a small number of very large customers with the budget to fund development. Having sold that business, ASI needed somewhere to point the autonomy stack it had built there. It found it within a year.
On 5 May 2025, twelve months after the Epiroc sale, ASI announced that it had “launched ASI Construction with SoftBank Group Corp.” That release describes ASI Construction as “ASI’s new business unit, which focuses on automating construction equipment to address growing construction demand and a dwindling labor supply,” and quotes Torrie saying it “will develop and operate a fleet of autonomous construction vehicles in the United States.” He put the mining connection on the record explicitly: “ASI Construction leverages ASI’s recent strategic divestment and departure from mining with the sale of ASI Mining to Epiroc.” No terms were disclosed for that launch.
That matters for how last week’s announcement reads. This is not SoftBank arriving at a company that had pivoted to construction on its own. SoftBank has been inside ASI’s construction business since the day it was created, and the $225 million and the joint venture are the third step in a relationship, not the first.
Analysis: this is the bet that construction is the next haul road. It is not obviously true. A mine site is a controlled environment with fixed routes, one owner and a safety regime built around autonomy. A highway widening or an airport apron has public traffic, multiple subcontractors, a changing site geometry and a general contractor who does not own most of the machines on it. Torrie’s list — roadways, airports, railways, waste management — is notably weighted toward the civil end of construction, which is the end that most resembles mining. That looks like a deliberate choice rather than an accident of phrasing.
Four Years of SoftBank, and the Same Bet Twice
The relationship goes back further still. On 7 June 2022, SoftBank Robotics America announced a “strategic development and equity partnership” with ASI aimed at outdoor automation — landscaping and logistics — and stated plainly that “as part of the agreement, SBRA has acquired a minority stake in ASI.” No amount was given. Torrie was quoted then too: “SoftBank Robotics America is leading the way in the scaling of robot commercialization and we are thrilled with the complementary strengths we are now fusing together.” Last week’s release names SoftBank Group Corp. rather than SoftBank Robotics America, and does not mention the 2022 partnership, the 2025 business-unit launch, or the stake either created.
Alongside ASI, SoftBank has been buying the same idea elsewhere. This is its second nine-figure commitment to construction-machine autonomy in just over five weeks: on 17 August, Gravis Robotics announced a $200 million Series A from SoftBank as the only named investor — also for retrofit autonomy, also OEM-agnostic, also aimed at machines contractors already own.
The two companies are not the same shape. Gravis is a 2022 ETH Zurich spinout whose product is autonomy on the excavator itself; ASI, founded in 2000, sells the layer above the machines, coordinating a fleet. But the thesis SoftBank is underwriting in both is identical, and it is a specific one: that the money in construction autonomy is in retrofitting the installed base rather than in selling new autonomous iron. That is close to the opposite of the bet an equipment maker like Caterpillar or Komatsu would naturally make, and it is worth noting that when Caterpillar did move on physical AI this month, it framed the work around inspection and situational awareness rather than machine control.
What We Don’t Know
- The joint venture’s size, structure and name. All three are undisclosed. Until they are public, the most precise thing that can be said is that SoftBank has committed more than $225 million across the two transactions.
- Whether the $225 million is equity, and on what terms. The release says “invested,” and does not characterise the instrument or give a valuation.
- Any construction deployment. No contractor, project or site is named in last week’s announcement. The May 2025 launch quotes Torrie saying ASI “counts John Deere, CNH, and other world leaders as its customers” for its construction product development, but neither document names a jobsite where autonomous construction vehicles are running.
- What the joint venture builds that ASI Construction does not. The release scopes the JV to “civil construction and material-handling” and the direct investment to “the broader construction market,” so a line is drawn — but it does not say what the new entity will develop, own or sell that the business unit launched in May 2025 does not.
- How the SoftBank holdings fit together. A minority stake taken by SoftBank Robotics America in 2022, a business unit launched with SoftBank Group Corp. in 2025, a joint venture and a $225 million investment in 2026. No public document we found sets out the relationship between them.